Thursday, September 3, 2009

Wednesday, September 2, 2009
Pending Home Sales on a Roll, Up for Sixth Straight Month
Contract activity for pending home sales has risen for six straight months, a pattern not seen in the history of the index since it began in 2001, according to the National Association of Realtors®.
The Pending Home Sales Index, a forward-looking indicator based on contracts signed in July, increased 3.2% to 97.6 from a reading of 94.6 in June, and is 12.0% higher than July 2008 when it was 87.1.The index is at the highest level since June 2007 when it was 100.7.
Lawrence Yun, NAR chief economist, said the housing market momentum has clearly turned for the better. “The recovery is broad-based across many parts of the country. Housing affordability has been at record highs this year with the added stimulus of a first-time buyer tax credit,” he said. “Other buyers are taking advantage of low home values before prices turn higher. Nationally, the typical mortgage payment now takes less than 25% of a middle-income family’s monthly income to buy a median priced home, with payment percentages so far in 2009 being the lowest on record dating back to 1970. As long as home buyers stay within their budget, mortgage payments will be very manageable,” Yun said.
NAR estimates that about 1.8 to 2.0 million first-time buyers will take advantage of the $8,000 tax credit this year, with approximately 350,000 additional sales that would not have taken place without the credit. Buyers have little time to act because they must complete the transaction by November 30, 2009 to qualify for the credit. Unless extended, contracts signed but not completed by that date will not be eligible- it is taking approximately two months to complete home sales in the current market.
The Pending Home Sales Index in the Northeast declined 3.0% to 78.8 in July but is 4.7% higher than July 2008. In the Midwest the index slipped 2.0% to 88.1 but is 8.1% above a year ago. In the South, pending home sales activity rose 3.1% to an index of 103.8 in July and is 12.0% above July 2008. In the West the index jumped 12.1% to 112.5 and is 20.0% above a year ago.
NAR President Charles McMillan, a broker with Coldwell Banker Residential Brokerage in Dallas-Fort Worth, said Congress needs to keep the momentum going. “Even with a good recovery taking place, the market is not yet back to normal. With a gradual absorption of inventory, we are on the cusp of a general stabilization in home prices,” he said. “To ensure that housing has a broad stimulus to the overall economy and stays on sound footing, we’re encouraging Congress to extend the tax credit into 2010, and to expand it to all buyers of primary residences. The faster we stabilize home prices, the fewer families will face foreclosure and the quicker credit can be extended to other sectors of the economy,” McMillan said.
NAR’s Housing Affordability Index (HAI) stood at 158.5 in July, below the peak set in April but is still 36.0 percentage points higher than a year ago. The HAI is a broad measure of housing affordability using consistent values and assumptions over time, which examines the relationship between home prices, mortgage interest rates and family income.
Yun expects existing-home sales to rise through the fourth quarter. “Unless the tax credit is extended, no one should be surprised to see home sales drop in the first quarter of next year,” he said. “However, the fundamentals of the housing market and the economy are trending up, and we expect home sales to generally pick up in the second quarter of 2010. The buyer psychology may be shifting from, ‘Why buy now when I can purchase later,’ to ‘I don’t want to miss out on a recovery.’”
September 2, 2009, RISMEDIA
The Pending Home Sales Index, a forward-looking indicator based on contracts signed in July, increased 3.2% to 97.6 from a reading of 94.6 in June, and is 12.0% higher than July 2008 when it was 87.1.The index is at the highest level since June 2007 when it was 100.7.
Lawrence Yun, NAR chief economist, said the housing market momentum has clearly turned for the better. “The recovery is broad-based across many parts of the country. Housing affordability has been at record highs this year with the added stimulus of a first-time buyer tax credit,” he said. “Other buyers are taking advantage of low home values before prices turn higher. Nationally, the typical mortgage payment now takes less than 25% of a middle-income family’s monthly income to buy a median priced home, with payment percentages so far in 2009 being the lowest on record dating back to 1970. As long as home buyers stay within their budget, mortgage payments will be very manageable,” Yun said.
NAR estimates that about 1.8 to 2.0 million first-time buyers will take advantage of the $8,000 tax credit this year, with approximately 350,000 additional sales that would not have taken place without the credit. Buyers have little time to act because they must complete the transaction by November 30, 2009 to qualify for the credit. Unless extended, contracts signed but not completed by that date will not be eligible- it is taking approximately two months to complete home sales in the current market.
The Pending Home Sales Index in the Northeast declined 3.0% to 78.8 in July but is 4.7% higher than July 2008. In the Midwest the index slipped 2.0% to 88.1 but is 8.1% above a year ago. In the South, pending home sales activity rose 3.1% to an index of 103.8 in July and is 12.0% above July 2008. In the West the index jumped 12.1% to 112.5 and is 20.0% above a year ago.
NAR President Charles McMillan, a broker with Coldwell Banker Residential Brokerage in Dallas-Fort Worth, said Congress needs to keep the momentum going. “Even with a good recovery taking place, the market is not yet back to normal. With a gradual absorption of inventory, we are on the cusp of a general stabilization in home prices,” he said. “To ensure that housing has a broad stimulus to the overall economy and stays on sound footing, we’re encouraging Congress to extend the tax credit into 2010, and to expand it to all buyers of primary residences. The faster we stabilize home prices, the fewer families will face foreclosure and the quicker credit can be extended to other sectors of the economy,” McMillan said.
NAR’s Housing Affordability Index (HAI) stood at 158.5 in July, below the peak set in April but is still 36.0 percentage points higher than a year ago. The HAI is a broad measure of housing affordability using consistent values and assumptions over time, which examines the relationship between home prices, mortgage interest rates and family income.
Yun expects existing-home sales to rise through the fourth quarter. “Unless the tax credit is extended, no one should be surprised to see home sales drop in the first quarter of next year,” he said. “However, the fundamentals of the housing market and the economy are trending up, and we expect home sales to generally pick up in the second quarter of 2010. The buyer psychology may be shifting from, ‘Why buy now when I can purchase later,’ to ‘I don’t want to miss out on a recovery.’”
September 2, 2009, RISMEDIA
Tuesday, September 1, 2009
Terriffic Trolley Tours
Innovative Marketing
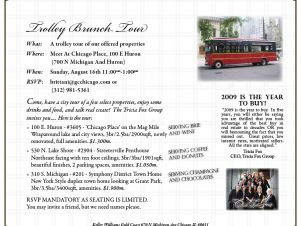
Tricia Fox has always done things a little bit differently from other real estate professionals in her downtown Chicago area. From art shows to shopping center kiosks to home-buying seminars that draw more than 500 people, Fox, broker of Tricia Fox Group of Keller Williams Luxury Real Estate in Chicago, does more than “take a listing, put it in the MLS, post it to a few websites and send out a postcard.”
So, when the weather turned cold, Fox decided to add luxury home tours by limo to her marketing repertoire. “Our offices are located on Michigan Avenue, and we specialize in properties in this area,” says Fox, who had 22 sales associates on her team and two staff members. The free limo tours took prospective buyers to several condominium listings in that area. But, it was so popular that Fox had to come up with a plan B. “We had such a great turnout that we decided to rent a trolley car so that we could seat more people,” she says. Fox recently took out her first trolley tour. “We had 32 seats, and they were all taken [15 couples]. Some of our team sales associates brought buyers on the tour, some sales associates waited at the properties,” she says. The group looked at seven resale properties and, according to Fox, three couples have taken a second look at some of the properties.
The trolley tours are free to prospective buyers and last about two hours. Each tour costs Fox about $1000 and she’s planning two a month. “Brunch is a good time of day for the tours,” says Fox.
Here are Fox’s tips for running a successful tour:
1. Plan ahead. The hardest part for Fox is the front-end planning. “You have to choose properties, make arrangements with owners [all properties are listed by Fox or someone on her team], decide who to invite and get the invitations out.” Fox has about 12 agents participate in the tours, so it’s vital to schedule several weeks in advance to ensure the entire group knows their assignments. “We have two agents at each site.”
2. Choose properties wisely. Fox only chooses vacant or sparsely furnished condos to show on the tour. “With so many people walking through the listing at once too much furniture makes it difficult,” she says. She also picks a price range for each tour. For example, one tour may feature lower-end properties that first time homebuyers or part-time residents may like; another tour might feature properties between $1 and $2 million. She then offers a mix of properties ranging from those with beautiful views to those with distinctive architecture.
3. Serve refreshments. Fox always serves refreshments at each property. “We may start with coffee at the first condo, then move on to wine and cheese. But, at the last property we always serve chocolates and champagne to make it festive,” she says.
4. Encourage conversation. Between properties, Fox visits in the trolley with each couple to answer questions. She also brings along a couple of mortgage brokers who can answer financing questions.
5. Use signs. Fox had some custom signs made that she can hang on the trolley for each tour. She also features brochures and signs at each listing.
6. Follow up. In addition to a feedback form she hands out, she has a follow up system for her team. “Individual agents follow up with the buyers and set up more appointments,” she says.
While she’s only done one tour, she’s learned a valuable lesson. “Next time, I would push people through the properties a little faster. We ended up with a lot of questions that could have been answered in the trolley on the way to the next property.”
It’s too soon to know exactly what kind of return on investment Fox will see. “Who knows what the actual return will be, but when you compare that cost to a print ad, the trolley is much more effective. It has the impact of personal touch. You can meet with people in person and really get to know them,” she says.
by Tracey Velt

Tricia Fox has always done things a little bit differently from other real estate professionals in her downtown Chicago area. From art shows to shopping center kiosks to home-buying seminars that draw more than 500 people, Fox, broker of Tricia Fox Group of Keller Williams Luxury Real Estate in Chicago, does more than “take a listing, put it in the MLS, post it to a few websites and send out a postcard.”
So, when the weather turned cold, Fox decided to add luxury home tours by limo to her marketing repertoire. “Our offices are located on Michigan Avenue, and we specialize in properties in this area,” says Fox, who had 22 sales associates on her team and two staff members. The free limo tours took prospective buyers to several condominium listings in that area. But, it was so popular that Fox had to come up with a plan B. “We had such a great turnout that we decided to rent a trolley car so that we could seat more people,” she says. Fox recently took out her first trolley tour. “We had 32 seats, and they were all taken [15 couples]. Some of our team sales associates brought buyers on the tour, some sales associates waited at the properties,” she says. The group looked at seven resale properties and, according to Fox, three couples have taken a second look at some of the properties.
The trolley tours are free to prospective buyers and last about two hours. Each tour costs Fox about $1000 and she’s planning two a month. “Brunch is a good time of day for the tours,” says Fox.
Here are Fox’s tips for running a successful tour:
1. Plan ahead. The hardest part for Fox is the front-end planning. “You have to choose properties, make arrangements with owners [all properties are listed by Fox or someone on her team], decide who to invite and get the invitations out.” Fox has about 12 agents participate in the tours, so it’s vital to schedule several weeks in advance to ensure the entire group knows their assignments. “We have two agents at each site.”
2. Choose properties wisely. Fox only chooses vacant or sparsely furnished condos to show on the tour. “With so many people walking through the listing at once too much furniture makes it difficult,” she says. She also picks a price range for each tour. For example, one tour may feature lower-end properties that first time homebuyers or part-time residents may like; another tour might feature properties between $1 and $2 million. She then offers a mix of properties ranging from those with beautiful views to those with distinctive architecture.
3. Serve refreshments. Fox always serves refreshments at each property. “We may start with coffee at the first condo, then move on to wine and cheese. But, at the last property we always serve chocolates and champagne to make it festive,” she says.
4. Encourage conversation. Between properties, Fox visits in the trolley with each couple to answer questions. She also brings along a couple of mortgage brokers who can answer financing questions.
5. Use signs. Fox had some custom signs made that she can hang on the trolley for each tour. She also features brochures and signs at each listing.
6. Follow up. In addition to a feedback form she hands out, she has a follow up system for her team. “Individual agents follow up with the buyers and set up more appointments,” she says.
While she’s only done one tour, she’s learned a valuable lesson. “Next time, I would push people through the properties a little faster. We ended up with a lot of questions that could have been answered in the trolley on the way to the next property.”
It’s too soon to know exactly what kind of return on investment Fox will see. “Who knows what the actual return will be, but when you compare that cost to a print ad, the trolley is much more effective. It has the impact of personal touch. You can meet with people in person and really get to know them,” she says.
by Tracey Velt
Savvy Buyers use Self-Directed IRA to Buy Homes
Nathan Foran used his self-directed IRA to buy a dilapidated foreclosed house in Richmond for $25,000 cash. Another $25,000 to $35,000 from the retirement account will go toward fixing up the property. He then hopes to rent it out for about $1,000 a month, money that will go straight into his retirement account.
Foran, 40, a San Anselmo real estate broker and investor, sees a lot of advantages in investing in real estate through his individual retirement account.
"The net rental income goes into the IRA, so its generating money tax deferred," he said. "Once I sell, the money also goes directly into the IRA without capital gains tax. If I hold onto it for five to seven years, it probably will be worth in the low $200,000s, so I'll get a sizable gain. If I find another property I think will appreciate faster, I can sell this and use the funds to invest in that one. The IRA is a good long-term investment tool."
With many properties at bargain-basement prices, more people have been turning to their self-directed IRAs as a ready source of capital to make real estate investments. Companies that manage self-directed IRAs say real estate investments by their clients are up as much as 30 percent over the past year.
But experts caution there are a range of potential issues and gotchas -including ones that could even disqualify the entire IRA.
Self-directed IRAs account for just 2 percent of the $4.2 trillion IRA market, but are among its fastest- growing segments. They allow access to a variety of investment vehicles beyond just stocks and bonds. The IRS closely regulates them, and any real estate investments must be handled by IRA custodian firms that hold the property inside the IRA. Can't live in property IRA owners can invest in any kind of real estate - raw land, commercial properties or residential rental properties. They cannot invest in a property they already own or plan to live in, however. The retirement funds "represent a large amount of untapped capital for investors that they can more actively manage," said Brad Hemstreet, vice president of sales and marketing for Equity Trust Co., a Cleveland company with $8 billion of IRA funds under management.
After the recent stock market downturn, "people are pulling out of Wall Street and want investments they understand and are comfortable with," he said. "Many people look at owning a property as a far better investment than owning a stock or bond." Mary Kay Foss, a CPA and director of the Danville office for accounting firm Greenstein, Rogoff, Olsen and Co., said using IRAs to buy real estate can negate many tax advantages. "Real estate is already one of the best investments you can have, tax-wise, because you can deduct all of your expenses, and when you sell it, you pay long-term capital gains (at 15 percent, much lower than income tax)," she said. "But if you have it in an IRA, none of the expenses are deductible. When it's sold, any profit is taxed when you take it out (of the IRA) as ordinary income."
Investing in real estate with a Roth IRA has fewer drawbacks, she said, because distributions are tax-free once the account has been in place for at least five years, although "you still have the downside that you can't deduct any expenses."
Must follow IRS rules. People who invest in real estate through an IRA have to make sure they adhere to IRS rules or they risk disqualifying the account, which carries heavy tax penalties. Neither they nor their relatives can live in the property. They cannot pay any expenses directly; everything from repairs to property taxes must be funded from the IRA. That means they must make sure their IRA has enough liquidity to handle expenses. If they have to add money, they pay a penalty.
"At this price point, I'm able to do the entire transaction with my IRA," Foran said about his $25,000 property. "I wanted to be very safe and make sure I have plenty of buffer in there so I won't have to do a capital contribution to keep that property afloat."
Companies that manage self-directed IRAs said they fully disclose all rules and recommend that investors educate themselves and consult their own accountants.
"Generally people in the real estate IRA business are very savvy about the market and investment properties," said Hugh Bromma, CEO of Oakland's Entrust Group, which has $4 billion in IRA funds under management. "They're picking up selected properties in areas that will be conducive to long-term appreciation."
About 30 percent of Entrust's clients invest in real estate, he said. Foran is among them. Entrust charges $250 a year to manage a single property, plus fees for purchasing the property.
Most IRA real estate investors buy properties with all cash, the simplest approach. If they don't have enough funds to do that, they can partner with other IRA account owners, or even partner with themselves, for instance paying half from their IRA and half from their personal savings. 30% down required a handful of banks offer mortgages to IRA investors, but they must put down at least 30 percent, and they pay a higher interest rate because the loans must be nonrecourse, meaning the banks cannot go after other assets.
Once IRA account holders reach age 70 1/2, they must start taking minimum required distributions from their account. What if they have a house held in the account and can't sell it? "You can take a portion of it and transfer it to yourself," said Kathy Holcomb, business development officer at Pensco Trust Corp., a San Francisco IRA management company.
Suzanne Gregg, an agent with Paragon Real Estate Group in San Francisco, has bought and flipped a couple of properties through her IRA and said she tripled her money.
"It's not like you just buy a stock online and forget about it; it's a little more hands on," she said. "It's a tangible asset you can see and manage."
Tuesday, September 1, 2009 (SF Chronicle)
Carolyn Said, Chronicle Staff Writer
Foran, 40, a San Anselmo real estate broker and investor, sees a lot of advantages in investing in real estate through his individual retirement account.
"The net rental income goes into the IRA, so its generating money tax deferred," he said. "Once I sell, the money also goes directly into the IRA without capital gains tax. If I hold onto it for five to seven years, it probably will be worth in the low $200,000s, so I'll get a sizable gain. If I find another property I think will appreciate faster, I can sell this and use the funds to invest in that one. The IRA is a good long-term investment tool."
With many properties at bargain-basement prices, more people have been turning to their self-directed IRAs as a ready source of capital to make real estate investments. Companies that manage self-directed IRAs say real estate investments by their clients are up as much as 30 percent over the past year.
But experts caution there are a range of potential issues and gotchas -including ones that could even disqualify the entire IRA.
Self-directed IRAs account for just 2 percent of the $4.2 trillion IRA market, but are among its fastest- growing segments. They allow access to a variety of investment vehicles beyond just stocks and bonds. The IRS closely regulates them, and any real estate investments must be handled by IRA custodian firms that hold the property inside the IRA. Can't live in property IRA owners can invest in any kind of real estate - raw land, commercial properties or residential rental properties. They cannot invest in a property they already own or plan to live in, however. The retirement funds "represent a large amount of untapped capital for investors that they can more actively manage," said Brad Hemstreet, vice president of sales and marketing for Equity Trust Co., a Cleveland company with $8 billion of IRA funds under management.
After the recent stock market downturn, "people are pulling out of Wall Street and want investments they understand and are comfortable with," he said. "Many people look at owning a property as a far better investment than owning a stock or bond." Mary Kay Foss, a CPA and director of the Danville office for accounting firm Greenstein, Rogoff, Olsen and Co., said using IRAs to buy real estate can negate many tax advantages. "Real estate is already one of the best investments you can have, tax-wise, because you can deduct all of your expenses, and when you sell it, you pay long-term capital gains (at 15 percent, much lower than income tax)," she said. "But if you have it in an IRA, none of the expenses are deductible. When it's sold, any profit is taxed when you take it out (of the IRA) as ordinary income."
Investing in real estate with a Roth IRA has fewer drawbacks, she said, because distributions are tax-free once the account has been in place for at least five years, although "you still have the downside that you can't deduct any expenses."
Must follow IRS rules. People who invest in real estate through an IRA have to make sure they adhere to IRS rules or they risk disqualifying the account, which carries heavy tax penalties. Neither they nor their relatives can live in the property. They cannot pay any expenses directly; everything from repairs to property taxes must be funded from the IRA. That means they must make sure their IRA has enough liquidity to handle expenses. If they have to add money, they pay a penalty.
"At this price point, I'm able to do the entire transaction with my IRA," Foran said about his $25,000 property. "I wanted to be very safe and make sure I have plenty of buffer in there so I won't have to do a capital contribution to keep that property afloat."
Companies that manage self-directed IRAs said they fully disclose all rules and recommend that investors educate themselves and consult their own accountants.
"Generally people in the real estate IRA business are very savvy about the market and investment properties," said Hugh Bromma, CEO of Oakland's Entrust Group, which has $4 billion in IRA funds under management. "They're picking up selected properties in areas that will be conducive to long-term appreciation."
About 30 percent of Entrust's clients invest in real estate, he said. Foran is among them. Entrust charges $250 a year to manage a single property, plus fees for purchasing the property.
Most IRA real estate investors buy properties with all cash, the simplest approach. If they don't have enough funds to do that, they can partner with other IRA account owners, or even partner with themselves, for instance paying half from their IRA and half from their personal savings. 30% down required a handful of banks offer mortgages to IRA investors, but they must put down at least 30 percent, and they pay a higher interest rate because the loans must be nonrecourse, meaning the banks cannot go after other assets.
Once IRA account holders reach age 70 1/2, they must start taking minimum required distributions from their account. What if they have a house held in the account and can't sell it? "You can take a portion of it and transfer it to yourself," said Kathy Holcomb, business development officer at Pensco Trust Corp., a San Francisco IRA management company.
Suzanne Gregg, an agent with Paragon Real Estate Group in San Francisco, has bought and flipped a couple of properties through her IRA and said she tripled her money.
"It's not like you just buy a stock online and forget about it; it's a little more hands on," she said. "It's a tangible asset you can see and manage."
Tuesday, September 1, 2009 (SF Chronicle)
Carolyn Said, Chronicle Staff Writer
Monday, August 31, 2009
Tuesday, August 25, 2009
First-Time Buyer Tax Credit Extension Possible
Bills to extend the maximum $8,000 tax credit for first-time home buyers, which expires Nov. 30, are pending in both the U.S. House and the Senate.
Sen. Christopher J. Dodd, a Connecticut Democrat and chairman of the Senate Banking, Housing, and Urban Affairs Committee, is co-sponsor of a bill with Georgia Republican Sen. Johnny Isakson that would raise the credit amount to a maximum of $15,000.
Senate Majority Leader Harry M. Reid of Nevada favors an extension of the current credit. He was quoted by the Las Vegas Sun saying, "It's something we can get done."
Odds are that the credit will be extended and broadened to cover all buyers next year, but the chances of the amount increasing aren’t as good, observers say.
Source: Washington Post Writers Group, Kenneth R. Harney (08/22/2009)
Sen. Christopher J. Dodd, a Connecticut Democrat and chairman of the Senate Banking, Housing, and Urban Affairs Committee, is co-sponsor of a bill with Georgia Republican Sen. Johnny Isakson that would raise the credit amount to a maximum of $15,000.
Senate Majority Leader Harry M. Reid of Nevada favors an extension of the current credit. He was quoted by the Las Vegas Sun saying, "It's something we can get done."
Odds are that the credit will be extended and broadened to cover all buyers next year, but the chances of the amount increasing aren’t as good, observers say.
Source: Washington Post Writers Group, Kenneth R. Harney (08/22/2009)
Existing Homes Selling Fast - Record Fast
The volume of home re-sales has been on the upswing for four consecutive months.
NEW YORK (CNNMoney.com) -- Sales of existing homes rose in July for the fourth consecutive month, lending support to economists who argue a recovery is near.
Sales of previously owned single-family homes were up 7.2% compared with June and 5% from July 2008, The National Association of Realtors (NAR) reported Friday. The monthly gain was the largest on record for existing-home sales, which NAR has tracked since 1999.
"The housing market has decisively turned for the better," said Lawrence Yun, NAR's chief economist. "A combination of first-time buyers taking advantage of the housing stimulus tax credit and greatly improved affordability conditions are contributing to higher sales."
July home sales hit an annualized rate of 5.24 million proprieties, marking the first breach of the 5 million annualized rate mark since last September, when they hit 5.1 million. Since then, they have stayed in a very narrow range, bouncing between between January's low of 4.49 million and October's high of 4.94 million.
The July performance far exceeded expectations: A consensus of real estate experts had forecast sales of 5 million.
Low prices
Of course, homes should be selling. Prices have fallen more than 32% from their peaks, set in the summer of 2006. Plus, mortgage rates near historic lows makes the cost of purchasing a home lower than they've been in nearly 20 years.
0:00 /3:11Home Depot sees housing recovery
"In some recovering markets like San Diego, Las Vegas, Phoenix and Orlando, the demand for foreclosed and lower priced homes has spiked, and a lack of inventory is becoming a common complaint," Yun said.
Overall though, the national inventory rose by more than 7% to 4.09 million units. That will continue to keep prices low, according to Mike Larson, a housing analyst with Weiss Research.
"There's a bifurcation of the market," he said. "There's excess supply putting downward pressure on prices and people respond to the lower prices by buying homes."
Housing is its most affordable in many years, he pointed out. "Falling prices is not part of the problem, they're part of the solution," he said.
Hurting home sales have been stubborn increases in job losses. More than 6.7 million jobs have been lost since the beginning of 2008.
That's one reason why Robert Dye, a senior economist for PNC Financial Services (PNC, Fortune 500), is keeping his optimism in check.
"I wouldn't go overboard on this number," he said. "The economy is still healing and will continue to run into some bumps. But it does bode very well for the future and shows buyer confidence is increasing."
There is one potential bump, however: The looming end of the first-time homebuyers credit. The credit gave first-time homebuyers an up to $8,000 refund on their taxes if they close on a deal before Dec. 1. That credit has been motivating buyers, and when it expires, demand could dry up.
"Just like with the cash-for-clunkers program, we run the risk of a letdown as the program runs its course," Dye said.
Where homes are selling
Regionally, the strongest market was the Northeast, where sales soared by 13.4% to an annualized rate of 930,000. That was 3.3% higher than last July. The median price of homes sold during the month was $236,700, off 15% from last year.
Midwest sales rose 10.9% to a 1.22 million rate, 8% higher year-over-year. Prices there have sunk 5.9% over the past 12 months to a median of $157,200.
In the South, sales were up 7.1% from June and 5.4% from last July to a rate of 1.95 million. Price have dropped 7.1% to $164,500 over the past 12 months.
The only region reporting a slip in sales was the West, where they fell 1.7% to a rate of 1.13 million. That was ahead of last July, however, by 1.8%. The median price there was $202,300, a whopping 28% below what is was a year ago.
First Published: August 21, 2009: 10:19 AM ET
Money.cnn.com
NEW YORK (CNNMoney.com) -- Sales of existing homes rose in July for the fourth consecutive month, lending support to economists who argue a recovery is near.
Sales of previously owned single-family homes were up 7.2% compared with June and 5% from July 2008, The National Association of Realtors (NAR) reported Friday. The monthly gain was the largest on record for existing-home sales, which NAR has tracked since 1999.
"The housing market has decisively turned for the better," said Lawrence Yun, NAR's chief economist. "A combination of first-time buyers taking advantage of the housing stimulus tax credit and greatly improved affordability conditions are contributing to higher sales."
July home sales hit an annualized rate of 5.24 million proprieties, marking the first breach of the 5 million annualized rate mark since last September, when they hit 5.1 million. Since then, they have stayed in a very narrow range, bouncing between between January's low of 4.49 million and October's high of 4.94 million.
The July performance far exceeded expectations: A consensus of real estate experts had forecast sales of 5 million.
Low prices
Of course, homes should be selling. Prices have fallen more than 32% from their peaks, set in the summer of 2006. Plus, mortgage rates near historic lows makes the cost of purchasing a home lower than they've been in nearly 20 years.
0:00 /3:11Home Depot sees housing recovery
"In some recovering markets like San Diego, Las Vegas, Phoenix and Orlando, the demand for foreclosed and lower priced homes has spiked, and a lack of inventory is becoming a common complaint," Yun said.
Overall though, the national inventory rose by more than 7% to 4.09 million units. That will continue to keep prices low, according to Mike Larson, a housing analyst with Weiss Research.
"There's a bifurcation of the market," he said. "There's excess supply putting downward pressure on prices and people respond to the lower prices by buying homes."
Housing is its most affordable in many years, he pointed out. "Falling prices is not part of the problem, they're part of the solution," he said.
Hurting home sales have been stubborn increases in job losses. More than 6.7 million jobs have been lost since the beginning of 2008.
That's one reason why Robert Dye, a senior economist for PNC Financial Services (PNC, Fortune 500), is keeping his optimism in check.
"I wouldn't go overboard on this number," he said. "The economy is still healing and will continue to run into some bumps. But it does bode very well for the future and shows buyer confidence is increasing."
There is one potential bump, however: The looming end of the first-time homebuyers credit. The credit gave first-time homebuyers an up to $8,000 refund on their taxes if they close on a deal before Dec. 1. That credit has been motivating buyers, and when it expires, demand could dry up.
"Just like with the cash-for-clunkers program, we run the risk of a letdown as the program runs its course," Dye said.
Where homes are selling
Regionally, the strongest market was the Northeast, where sales soared by 13.4% to an annualized rate of 930,000. That was 3.3% higher than last July. The median price of homes sold during the month was $236,700, off 15% from last year.
Midwest sales rose 10.9% to a 1.22 million rate, 8% higher year-over-year. Prices there have sunk 5.9% over the past 12 months to a median of $157,200.
In the South, sales were up 7.1% from June and 5.4% from last July to a rate of 1.95 million. Price have dropped 7.1% to $164,500 over the past 12 months.
The only region reporting a slip in sales was the West, where they fell 1.7% to a rate of 1.13 million. That was ahead of last July, however, by 1.8%. The median price there was $202,300, a whopping 28% below what is was a year ago.
First Published: August 21, 2009: 10:19 AM ET
Money.cnn.com
Subscribe to:
Posts (Atom)